Every figure on this page is drawn from DiamondRock Hospitality's public filings, releases and investor presentations over Mark Brugger's tenure as co-founder, chief financial officer and, from 2008 to 2024, chief executive. Results are DiamondRock's. They are shown as evidence of how the work was done, not as a promise of what advice will produce.
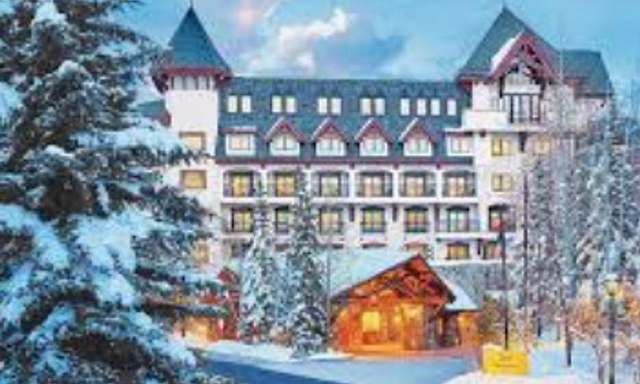
The Hythe, Vail
Outperformance against the lodging REIT peer set
DiamondRock's total shareholder return beat the peer average over every period measured, to April 30, 2024.
Three years
+23.8 ptsahead of the peer average in total shareholder return
Since September 2008, when Mark became CEO
+40.5 ptsahead of the peer average in total shareholder return
2ndhighest total return in the lodging REIT peer set over the trailing three- and five-year periods to April 2024
Top quartiletotal shareholder return as a public REIT chief executive
#1lodging REIT by total return in its first full calendar year public
Source: FactSet as of April 30, 2024, total returns. Three-year peer set: HST, PK, RLJ, XHR, SHO, PEB, BHR, AHT; since-2008 peer set: HST, SHO, AHT. Outperformance is DiamondRock's total return less the peer average, in percentage points. Past performance is not indicative of future results.
Growing earnings into the basis
DiamondRock bought resorts at full-looking multiples, then grew their earnings into the price.
13resorts in the portfolio
$1.2Binvested
13.1x → 10.9xaverage EBITDA multiple, at purchase and on 2019 earnings
+$40.5Mof added annual EBITDA
Resort
Total investment
Multiple at purchase
2019 multiple
2019 yield on cost
The Lodge at Sonoma Sonoma, California
$40M
10.7x
5.7x
17.5%
Renaissance Charleston (now The Lindy) Charleston, South Carolina
$43M
11.9x
7.0x
14.3%
L'Auberge de Sedona Sedona, Arizona
$67M
15.8x
8.6x
11.6%
Vail Marriott (now The Hythe) Vail, Colorado
$96M
13.4x
8.7x
11.5%
Hilton Burlington Lake Champlain Burlington, Vermont
$64M
16.5x
8.9x
11.2%
Portfolio as reported in February 2020. Yield on cost is 2019 EBITDA over total investment, before FF&E reserve. Implied EBITDA derived from multiples DiamondRock disclosed. Source: DiamondRock investor presentations, February and June 2020.
Five repositionings
Each one turned on identifiable levers rather than on market growth: brand, operator, product and revenue mix, on a defined capital budget.
The Lodge at Sonoma
Sonoma, California · Renaissance to Autograph Collection, with an operator change
10.7x→5.7x
EBITDA multiple at purchase, and on 2019 EBITDA
17.5%
2019 yield on total cost
Acquired
October 2004 · $31.5M · 182 keys (about $173K per key) · 10.7x EBITDA
Repositioning
Renaissance to Autograph Collection (July 2021); management moved from Marriott to Sage Hospitality; new Michael Mina restaurant
Capital
About $40M total investment through 2019; about $10M for the 2021 transformation
Outcome
2019 EBITDA about $7.0M, a 17.5% yield on total cost; RevPAR share up 20 points on 2019 in the first half of 2021
Levers used: basis · capital program · brand repositioning · operator change · revenue mix
The Hythe, Vail
Vail, Colorado · Vail Marriott Mountain Resort to Luxury Collection
$305K
basis per key at year-end 2021, against ski-resort trades of $1–2M per key
13.4x→8.7x
EBITDA multiple at purchase, and on 2019 EBITDA
Acquired
June 2005 · $64.4M · 344 keys (about $187K per key) · 13.4x EBITDA
Repositioning
Vail Marriott Mountain Resort to The Hythe, a Luxury Collection Resort (completed Q4 2021)
Capital
Multi-year renovation of about $40M; $8.4M of incremental capital for the luxury conversion
Outcome
2019 EBITDA about $11M on $96M invested; the resort rebuilt in phases, then moved up a brand tier in one of the most supply-constrained markets in the country, at a fraction of what new product would cost
Levers used: basis in a supply-constrained market · capital program · brand tier move
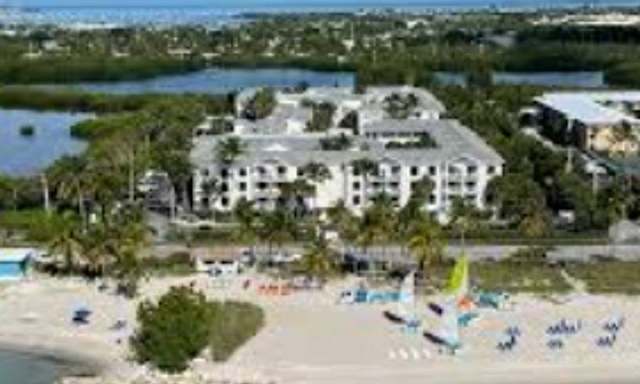
Margaritaville Beach House, Key West
Key West, Florida · Sheraton Suites to independent to Margaritaville
~2x
EBITDA: $7.3M purchase-year forecast to about $14M expected for 2021
+22 pts
market share versus 2019 after removing the flag
Acquired
July 2015 · $94.0M · 184 suites ($511K per key) · 7.1% cap rate
Repositioning
Sheraton Suites to independent Barbary Beach House (2020), then to Margaritaville Beach House (November 2021)
Capital
About $11M for the independent conversion; $3.5M for the Margaritaville conversion
Outcome
About $1.5M a year of brand fees removed; after Hurricane Irma set the plan back in 2017, the hotel was de-flagged, repositioned as an independent and moved to a lifestyle brand with its own demand
Levers used: brand repositioning, including de-flagging · channel and fee cost · capital program
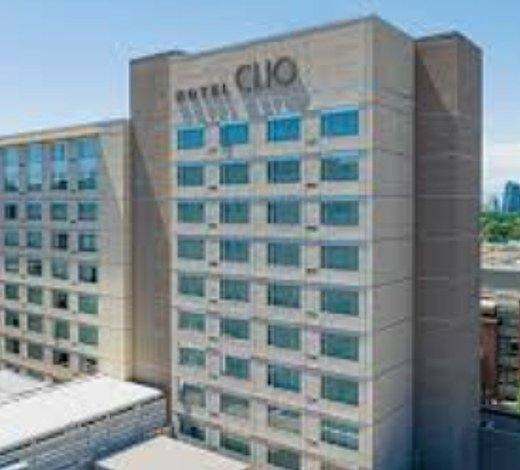
Hotel Clio, Denver
Cherry Creek, Denver · JW Marriott to Luxury Collection, March 2022
$3.6M
of conversion capital to move the hotel into the Luxury Collection
11.5x
EBITDA multiple at purchase, 7.5% cap rate
Acquired
May 2011 · $72.6M · 196 keys ($370K per key)
Repositioning
$2.4M restaurant repositioning (2019), then conversion to the Luxury Collection in March 2022
Capital
$3.6M of incremental capital for the conversion
Outcome
A well-bought urban-submarket asset moved up a tier on a small, targeted budget
Levers used: targeted capital · brand tier move
The Lindy, Charleston
Charleston, South Carolina · Renaissance, repositioned and renamed
14.3%
2019 yield on total cost: EBITDA up about 75% while the basis rose about 10%
11.1x→7.0x
forecast EBITDA multiple at purchase, and on 2019 earnings
Acquired
2010 · $39.0M · 166 keys (about $235K per key) · 11.1x forecast EBITDA of $3.5M, bought in the 2010 downturn
Repositioning
Successive renovations and a $2.1M food and beverage repositioning; renamed The Lindy
Capital
About $43M total investment through 2019
Outcome
2019 EBITDA about $6.1M; a quality asset bought in a downturn, in a market where new supply is hard to deliver
Levers used: basis bought in a downturn · food and beverage repositioning
The wider record
The same discipline, a brand or operator change on a defined capital budget, applied to urban assets as well as resorts.
The Gwen, Chicago
Conrad to Luxury Collection (2015), with a new operator
$25–27M rebranding and guest-room program
+10% ADR in 2017, the first full year after rooms were finished
+7 pts RevPAR market share by 2019
The Dagny, Boston
Hilton to independent (August 2023); 29 keys added
$32M total program, including the added rooms
29 keys added to the hotel
Cavallo Point, Sausalito
Acquired 2018 for $152M, off-market
OP units part of the price paid in operating partnership units, a structure that met the seller's needs
Relationship not the highest bid, is how the asset was found
48hotels acquired or sold, across luxury resorts, lifestyle and urban hotels
6brand conversions within $1B+ of renovations: Sonoma, Vail, Cherry Creek, Key West, Chicago and the Lexington, New York
$1Bof revenue, $3.5 billion of assets and 9,000 rooms, scaled from zero
$1Bof capital distributed to public shareholders
These transactions were executed on behalf of, and with the capital and teams of, DiamondRock Hospitality Company, where Mr. Brugger served as co-founder and chief financial officer and, from September 2008 to April 2024, as chief executive officer. They are presented as evidence of relevant experience and are not the track record of Elmsworth Advisors. Not every DiamondRock investment was profitable, and several were sold below cost. Figures described as projected or underwritten were DiamondRock forecasts made at the time, not realized results. Case study figures are drawn from DiamondRock public filings, releases and investor presentations; implied EBITDA and yields are derived from multiples DiamondRock disclosed. Photographs show hotels owned by DiamondRock during Mr. Brugger's tenure and are not assets of Elmsworth. Past performance is not indicative of, and provides no guarantee of, future results.